Most dental plans cover orthodontics only for dependents under a stated age, with a separate lifetime maximum and a partial payout. Medicaid can cover medically necessary braces for children under 21 through EPSDT, and standard medical insurance pays only in narrow, medically necessary circumstances. Your next move: find out which category your plan falls into, then ask your orthodontist’s office for a written predetermination before treatment starts.
TL;DR:
- Medicaid covers medically necessary braces for children under 21 through EPSDT, but eligibility and criteria vary by state and case.
- Dental plans typically cover a portion of orthodontic treatment for dependents, with a separate lifetime maximum, and in-network providers usually offer better coverage.
- Prior authorization and detailed documentation from the orthodontist are crucial to improve approval chances and should be requested and submitted before starting treatment.
- Families often still pay significant out-of-pocket costs since most plans cover only part of the expense and treat braces as a medical expense eligible for HSA or FSA funds.
- Verifying coverage, requesting a predetermination, and documenting all communications and decisions are key steps in avoiding surprises and successful appeals if denied.
Table of Contents
- How orthodontic coverage splits between dental plans, medical plans, and Medicaid
- What counts as medically necessary orthodontic care
- How to verify benefits, request a predetermination, and appeal a denial
- Paying for braces when coverage falls short
- How Sobal Health helps you sort out orthodontic coverage
- One priority, and the mistakes we see most
- Talk to Sobal Health about your coverage options
- FAQ
- Sources
How orthodontic coverage splits between dental plans, medical plans, and Medicaid
We get this question constantly, and the confusion makes sense. Orthodontic coverage doesn’t live in one tidy place. It depends on whether you’re looking at a dental plan, a medical plan, or Medicaid, and each handles braces differently.
Dental plans with an orthodontic rider typically cover a portion of treatment, often for dependents only, up to a separate lifetime maximum. Once you hit that cap, the plan stops paying regardless of how long treatment continues. In-network orthodontists usually get you the best rate on the covered portion, while going out-of-network can shrink what the plan pays or raise your share.
On the Marketplace, pediatric dental is one of the essential health benefits that plans must make available for children up through age 18. Adult dental coverage, including adult orthodontics, is optional and often sold as an add-on or a separate standalone policy.
Medicaid works differently again. Through EPSDT coverage and Medicaid ABA therapy, states must cover medically necessary diagnostic and treatment services for eligible children under 21, but each state defines medical necessity and reviews cases individually.
Here’s the quick breakdown:
- Dental plans: partial coverage for dependents, separate lifetime cap, network rules apply
- Marketplace plans: pediatric dental is required to be offered; adult orthodontics is optional
- Medicaid/EPSDT: covers medically necessary orthodontics for eligible children under 21, with state-specific criteria
- Standard medical plans: pay only when orthodontics treats a diagnosed medical condition, not cosmetic alignment
What counts as medically necessary orthodontic care
This is where families get stuck, and it’s worth slowing down. “Medically necessary” isn’t a feeling the orthodontist has. It’s a standard someone else has to agree with, usually a state dental consultant or a plan’s reviewer.
Under EPSDT, children under 21 are entitled to medically necessary services, but states set their own criteria and make determinations case-by-case. That means the same bite problem might qualify in one state and get denied in another.
The American Association of Orthodontists has proposed a definition of medically necessary orthodontic care along with auto-qualifiers, conditions that tend to support a stronger case. These aren’t a federal mandate, but they give you language to use with your orthodontist and your insurer.
Here’s what tends to move a case forward:
- Get a written clinical narrative from the orthodontist describing the functional problem, not just the cosmetic one.
- Gather diagnostic records, including photos, cephalometric X-rays, and bite measurements.
- Ask whether your state uses a scoring system for orthodontic medical necessity, and request the score sheet.
- Submit everything together rather than piecemeal, since partial submissions slow down reviews.
- Track the timeline, since prior authorization decisions can take weeks.
Pro Tip: Ask your orthodontist’s office whether they’ve worked with your specific plan or state Medicaid program before. Offices that submit these cases regularly usually know which documentation gets approved fastest.
How to verify benefits, request a predetermination, and appeal a denial
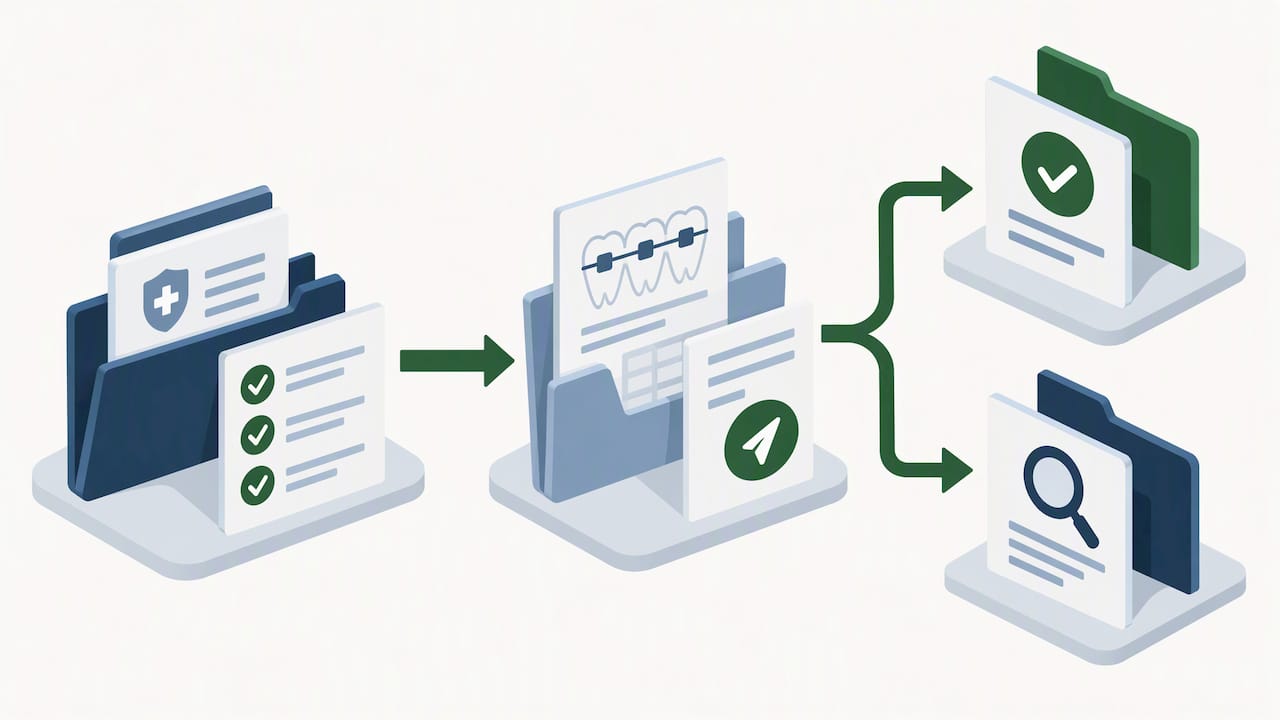
Treat this like a short project with a checklist, not a mystery. Start by pulling your plan documents, whether that’s a dental summary of benefits, an orthodontic rider, or your Medicaid member handbook, and look specifically for the words “orthodontic,” “lifetime maximum,” and “age limit.”
Call your insurer and ask these questions directly:
- Is orthodontic treatment a covered benefit under my plan, and what’s the lifetime maximum?
- Is there an age cutoff for dependents, and does it apply to me or my child?
- Does coverage differ between in-network and out-of-network orthodontists?
- Is prior authorization or predetermination required before treatment starts?
- What documentation does the plan need to process a predetermination?
Then ask your orthodontist’s office for a formal predetermination request, a detailed superbill with procedure codes, and a clinical narrative if medical necessity applies. Dental plans that cover orthodontics commonly pay a partial share of charges against a separate lifetime maximum, which is exactly why getting that predetermination in writing before treatment begins matters so much.
If you’re denied: request the denial in writing with the specific reason, file an internal appeal with your orthodontist’s clinical narrative attached, and if that fails, ask about external review or your state’s Medicaid fair hearing process. We’ve written more detail on this process in our guide to handling a denied health insurance claim, which covers the same appeal mechanics that apply to dental and orthodontic denials.
Paying for braces when coverage falls short
Even with a good dental plan, most families still owe a meaningful chunk out of pocket. If a plan pays roughly a partial share of orthodontic charges up to a lifetime maximum, a treatment plan priced in the typical cost range can still leave you covering a substantial portion yourself.
The good news: braces qualify as a medical expense under IRS Publication 502, which means HSA and FSA funds can pay for them, often making a real dent in the after-tax cost. Just confirm the timing rules with your plan administrator, since FSA funds are typically use-it-or-lose-it within the plan year.
Clinic payment options vary, so compare them carefully:
- In-house installment plans, often interest-free if paid within the promotional window
- Down payment plus monthly billing, spreading the lifetime-max gap over the treatment period
- Third-party medical financing, which can carry retroactive interest if a balance isn’t paid off in time, so read the terms closely
- State Medicaid global fee arrangements, which in some cases let treatment continue even after a child ages out of eligibility if the course of care began while the child was still covered
Pro Tip: Before signing up for a medical credit card promo, ask the orthodontist’s billing office if they offer an interest-free in-house plan instead. It’s usually the lower-risk option.
How Sobal Health helps you sort out orthodontic coverage
We work with families to find personal and family coverage that fits their situation, and dental benefits questions come up often. As independent brokers, we can review your current plan or a Marketplace option side by side with you, point out whether pediatric dental is embedded or sold separately, and flag the lifetime maximums and age limits buried in the fine print before you commit.
We also help you prepare for an orthodontic predetermination or appeal by walking through what documentation your plan or state Medicaid program typically wants to see. If you’re starting a consultation with us, bring your insurance card, any orthodontist estimate or treatment plan, and a copy of any denial letter you’ve received. It saves time and gets you a clearer answer faster.
One priority, and the mistakes we see most
If you take one thing from this: verify your plan type and request a predetermination before treatment starts. Some families assume adult orthodontics is automatically covered, or skip the predetermination step entirely and get surprised by a denial. Document everything, and always ask for denial reasons in writing.
— Bernie S
Talk to Sobal Health about your coverage options
A short conversation with an independent broker can save you from guessing. When families come to us with orthodontic questions, we typically help with:
- Reviewing your current dental or medical plan for orthodontic benefit language
- Identifying Marketplace or private plans that include pediatric dental coverage
- Walking through enrollment options if your current plan falls short
Bring your insurance card and any orthodontist estimate, and we’ll go through it with you. Reach out through our personal and family insurance page to set up a time to talk, whether you’re choosing new coverage or just trying to make sense of what you already have.
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.
FAQ
What insurance will cover orthodontics?
Dental plans with an orthodontic rider commonly cover braces for dependents up to a lifetime maximum, while Medicaid’s EPSDT benefit can cover medically necessary orthodontics for eligible children under 21. Standard medical insurance covers orthodontics only in narrow cases tied to a diagnosed medical condition, not cosmetic straightening.
Is $5,000 expensive for braces?
Orthodontic treatment plans vary, and whether it feels expensive depends heavily on your coverage. If your dental plan pays roughly half of charges up to its lifetime maximum, as many plans do, you could still owe a substantial portion yourself, which is why checking your benefit before starting treatment matters.
Can I pay $100 a month for braces?
Many orthodontic offices offer in-house installment plans with monthly payments varying depending on total cost, down payment, and length of the plan. Ask the billing office directly about their payment structure and whether an interest-free option is available before agreeing to third-party financing.
Is $7,000 a lot for braces?
Treatment plans vary in cost, with higher pricing often reflecting more complex cases or extended treatment time. Whether it’s manageable usually comes down to your dental coverage, your lifetime maximum, and whether you can pair HSA or FSA funds with a payment plan to offset the cost.
Sources
- Healthcare
- Medicaid
- Publication 502, Medical and Dental Expenses | IRS
- Paying for orthodontics | Fair Health
