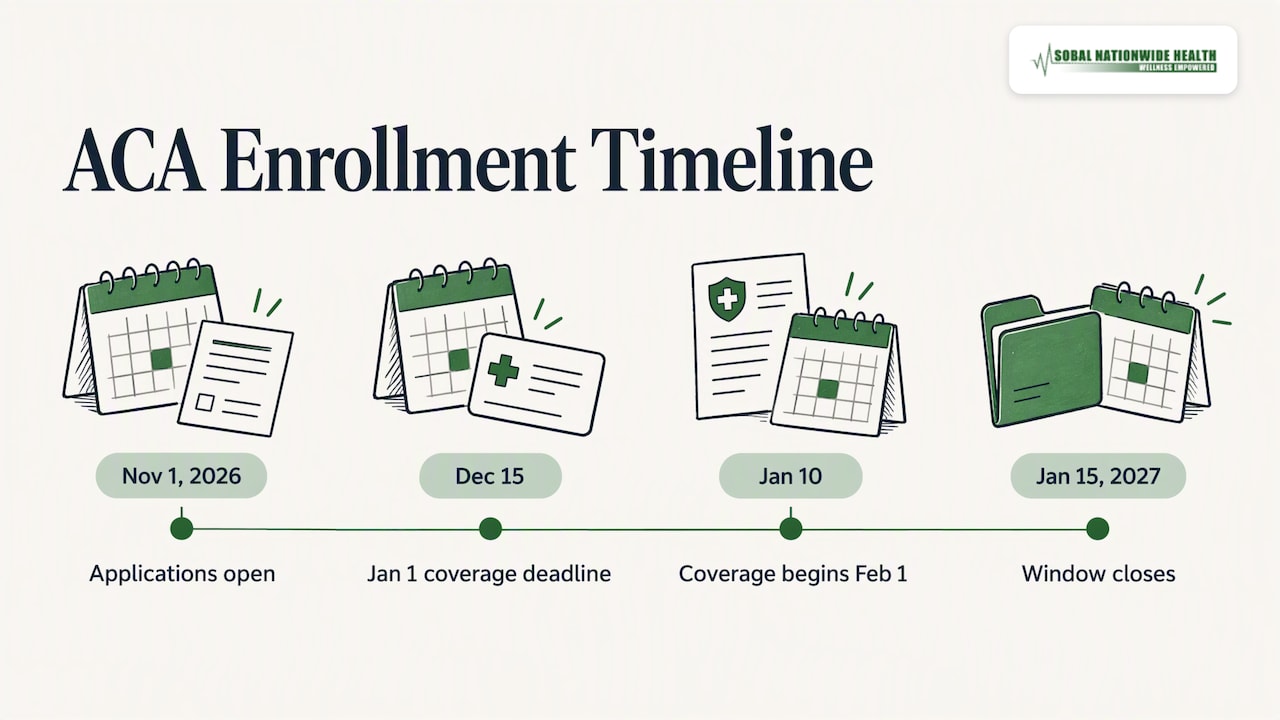
Open enrollment for 2027 ACA Marketplace coverage starts on November 1, 2026. On HealthCare.gov it runs through January 15, 2027, but the date that matters most is December 15, 2026. Pick a plan by then and coverage starts January 1. Pick one from December 16 through January 15 and coverage generally starts February 1.
Medicare has its own window, October 15 to December 7. Private plans and employer plans follow different rules again. Below, I walk through each one in plain English, with a special focus on what it means if you are self-employed or run a small business.
TL;DR
- Marketplace (HealthCare.gov): November 1, 2026 to January 15, 2027. Enroll by December 15 for a January 1 start.
- Medicare: October 15 to December 7. Changes take effect January 1, 2027.
- Some state-run exchanges set their own dates, so check your state’s site before you plan around January 15.
- Miss the window? A qualifying life event may open a Special Enrollment Period. Private plans and small-group coverage don’t follow the same calendar.
- Self-employed? This is the best time of year to re-check your income estimate and compare private options.
Table of Contents
- The 2027 open enrollment dates at a glance
- ACA Marketplace: what to know about the December 15 and January 15 dates
- Medicare open enrollment is a different calendar
- Why open enrollment matters more when you’re self-employed
- A simple checklist for the next few weeks
- Marketplace vs private plans: how to compare
- What if you miss open enrollment?
- Small business owners: your timeline is different
- Our perspective: why we tell people to start early
- Get help comparing your 2027 options
- FAQ
- Sources
The 2027 open enrollment dates at a glance
Here is the short version, by type of coverage.
| Coverage type | Window for 2027 coverage | Coverage starts |
|---|---|---|
| ACA Marketplace on HealthCare.gov | Nov. 1, 2026 to Jan. 15, 2027 | Jan. 1 if you enroll by Dec. 15; generally Feb. 1 after that |
| Medicare (Advantage and Part D changes) | Oct. 15 to Dec. 7, 2026 | Jan. 1, 2027 |
| Small employer group plans | Set by the employer and carrier | Depends on the plan year |
| Private medically underwritten plans | Not tied to the Marketplace calendar | Depends on approval and the carrier |
The Marketplace date is the one most people search for, so let’s start there.
ACA Marketplace: what to know about the December 15 and January 15 dates
If you shop on HealthCare.gov, HealthCare.gov says you can apply for 2027 coverage or update your application starting November 1. The window closes January 15, 2027.
So why do I keep saying December 15? Because it is the deadline for a January 1 start. Think of it as the “no gap” date. If you pick a plan on, say, January 10, you will usually wait until February 1 for coverage to begin. That can leave you uncovered for a month.
You may also have seen headlines that the window would shrink to end on December 15. A federal rule from 2025 did set out a shorter, standardized window beginning with plan year 2027. The current HealthCare.gov schedule still runs through January 15, but dates have moved before. My advice is simple: treat December 15 as your real deadline, and you are safe either way.
State-run exchanges can differ
Not every state uses HealthCare.gov. Some states run their own marketplaces and set their own end dates, some earlier and some later. Most states we serve use the federal schedule, but if your state has its own exchange, confirm the closing date on that exchange’s website.
The same window applies off the Marketplace, too. If you buy an ACA-compliant plan directly from an insurer, you are generally on the same annual calendar.
Medicare open enrollment is a different calendar
If you or a parent is on Medicare, do not mix up the two. Medicare Open Enrollment runs October 15 to December 7, and the changes you make take effect January 1. As I write this, that window is already open.
Medicare’s own guide suggests you start comparing your current coverage with 2027 options before Open Enrollment begins on October 15. Missing the December 7 date can mean staying in your current plan for another year, even if the Marketplace window is still open.
This matters for a specific group: people moving from Medicare to a Marketplace plan, or couples where one spouse is 65 and the other is not. Each person follows their own program’s dates.
Why open enrollment matters more when you’re self-employed
When you work for an employer, HR hands you a packet. When you work for yourself, you are the HR department. Three things make this season especially important for freelancers, 1099 contractors and owners.
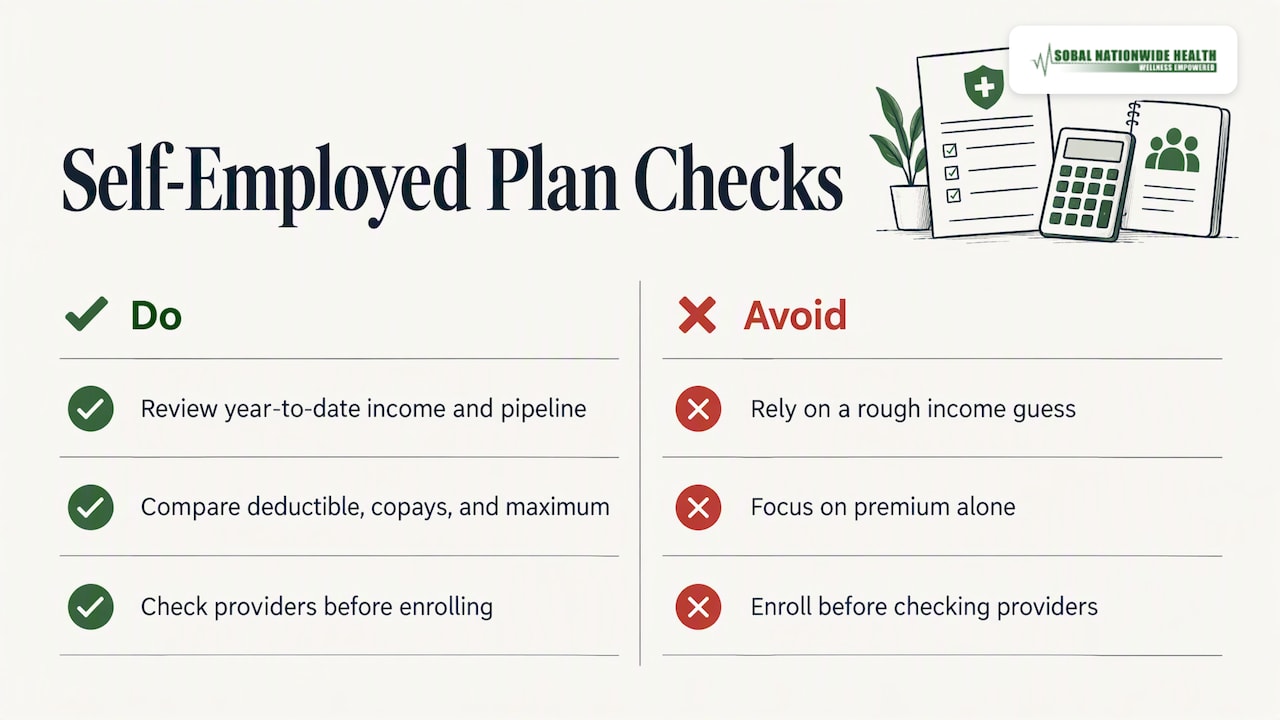
Your subsidy depends on your income guess. Premium tax credits are based on your estimated household income for the year ahead. If your income swings, a rough guess in November can turn into a surprise at tax time. Take an hour now to look at your year-to-date numbers and your pipeline.
The premium is only the way in. The premium gets you in the door. What you pay once you use care depends on the deductible, copays and out-of-pocket maximum, which acts as a financial safety net. A low-premium plan with a high deductible can cost more over a year than a pricier plan if someone in your family needs care.
Your network is part of the price. If your doctor or children’s hospital is not in network, the cheapest plan stops being cheap. Check providers before you click enroll, not after.
If your income is above the subsidy range, see our guide on ACA subsidy income limits to understand where the line falls for your household size. And if you are already above it, our piece on open enrollment 2027: private plans vs Marketplace goes deeper.
A simple checklist for the next few weeks
Here is the order I walk clients through. You can do it in a single evening.
- Gather your numbers. Last year’s income, this year’s income so far, and a realistic estimate for 2027. Include spouse income if you file jointly.
- List your must-haves. Doctors, hospitals, prescriptions, and any planned procedures.
- Decide how much risk you can carry. Look at the out-of-pocket maximum, not just the deductible. Ask yourself whether you could write that check in a bad year.
- Compare more than one type of plan. Marketplace plans are one option. Private plans are another.
- Confirm the start date. Applying alone does not start coverage; the first premium payment and the carrier’s approval matter. Our guide on health insurance effective dates explains the details.
- Aim for December 15. Leave a few days of cushion in case of a hiccup with documents or payment.
Marketplace vs private plans: how to compare
Many of the people who contact us are in one of two camps. Some earn too much to get subsidies and feel they are paying full price for a narrow network. Others are simply confused by the Marketplace and want a straight answer.
Private, medically underwritten plans are an option worth a look. They are not ACA Marketplace plans, so the carrier looks at your health history when you apply. For healthy people that can mean lower premiums and, often, a broader PPO network. For people with certain conditions, underwriting may mean a decline or limits on what is covered. That tradeoff is exactly why you should talk it through with a broker before deciding. Our explainer on how medically underwritten insurance works covers who it fits.
If you are still weighing network types, this breakdown of PPO vs HMO plan differences is a helpful starting point.
Here is a simple way to think about it:
| Question | Marketplace plan | Private underwritten plan |
|---|---|---|
| When can I enroll? | During open enrollment, or with a qualifying life event | Not tied to the Marketplace calendar, subject to approval |
| Can I get subsidies? | Yes, if your income qualifies | No |
| Does health history matter? | No | Yes, the carrier reviews it |
| Typical network | Often narrower, varies by plan | PPO options with a nationwide network are available |
Neither is right for everyone. If you get a subsidy that makes the Marketplace plan affordable, it is often the best deal. If you don’t, it is worth a side-by-side comparison. For a longer look at what to ask, read our 10 broker questions for self-employed buyers.
What if you miss open enrollment?
You have some options, but not as many as people think.
Special Enrollment Periods
Special Enrollment Periods are available outside open enrollment for qualifying life events like moving, marriage or losing other coverage. The CMS plan basics guide also notes that consumers can enroll during open enrollment or an applicable SEP, and that Medicaid and CHIP applications are accepted at any time.
An SEP generally gives you a limited time to act after the event, so do not wait. If you are in Florida, we have a guide on whether you qualify for a Special Enrollment Period.
Between jobs
If you just left a job, you are not stuck. You can compare COBRA with a Marketplace plan within the allowed window. Our guide on COBRA vs Marketplace after a job loss walks through the 60-day timeline.
Coverage that doesn’t follow the calendar
Some other products work outside open enrollment, including accident, critical illness and fixed indemnity plans. They are not a replacement for major medical coverage, but they can fill gaps. Ask what they do and do not cover before you buy.
Small business owners: your timeline is different
If you have employees, group coverage is not bound by the individual open enrollment dates. According to CMS, small employers in the SHOP program can enroll in group coverage at any time of year, working with issuers or registered agents and brokers to set their own enrollment periods.
That gives you flexibility, but it also means no one is reminding you. Pick a renewal date that does not collide with your busiest season, and give employees a few weeks to choose. If you want help with the options, our business health insurance page is the place to start.
Our perspective: why we tell people to start early
We are licensed independent brokers, and every fall we see the same pattern. People wait until the last week of the window, get overwhelmed by plan names, and pick whatever looks cheapest. Then they find out in March that their doctor is out of network.
We built Sobal Health around a different approach. We work with self-employed people, families and small businesses in 31 states, and we offer access to private, medically underwritten plans as well as ACA Marketplace coverage, so you can compare both. There is no sales pressure. Our job is to explain the choices in plain English, in English or Spanish, and let you decide.
One thing we say often: a plan is not a good deal because the premium is low. It is a good deal when the premium, the deductible, the network and the out-of-pocket maximum all fit your life. Some clients have told us they saved up to $400 per month after comparing, but your result depends on your age, health, state and income, and we won’t promise a number before we have looked at your situation.
If you are not sure which route fits, give yourself time. A calm comparison in early November beats a rushed one on December 14.
— Bernie S
Get help comparing your 2027 options
If you would like a second set of eyes, we can walk through your income, doctors and budget, and show you Marketplace and private options side by side. Start on our personal and family insurance page or visit sobalhealth.com to reach a broker directly.
FAQ
When does open enrollment start for 2027 health insurance?
For ACA Marketplace plans, it starts November 1, 2026. Medicare open enrollment started earlier, on October 15, 2026. Employer plans have their own dates, so ask your HR team.
What is the deadline to get coverage starting January 1, 2027?
Enroll by December 15, 2026. If you pick a plan between December 16 and January 15, coverage generally starts February 1. Because deadlines can shift and some states run their own exchanges, confirm the date on your state’s marketplace site.
Can I get health insurance after open enrollment ends?
Yes, in some cases. A qualifying life event such as moving, marriage, a new baby or losing other coverage can open a Special Enrollment Period. Medicaid and CHIP accept applications all year. Private plans have their own application rules and require approval.
Is Medicare open enrollment the same as Marketplace open enrollment?
No. Medicare runs October 15 to December 7, and the Marketplace starts November 1. They are separate programs with separate deadlines, so check the one that applies to you.
Do I have to re-enroll every year?
It is smart to review your plan every year, even if it renews automatically. Premiums, networks and your own income can change, and that affects what you pay.
Sources
- HealthCare.gov: When can you get health insurance?
- HealthCare.gov: Health coverage for self-employed
- CMS: 2025 Marketplace Integrity and Affordability Final Rule
- CMS: Affordable Care Act Basics PY 2027
- Medicare: Open Enrollment
- Medicare & You 2027
- Medicare: Joining a plan
- IRS Publication 974
